
Urology procedures cover a wide range of surgical and medical interventions used to diagnose and treat conditions of the urinary tract and the male and female reproductive systems. Because these procedures are both common and expensive, most health insurance policies provide coverage for them, including specific conditions such as urinary obstruction and urinary tract infections. Treatment can range from fast, minimally invasive checkups all the way to robot-assisted, complex surgeries, and the substantial amount of money typically required for doctor consultation, diagnosis, treatment, and ongoing management is exactly why insurance coverage matters across this category rather than just for the most severe cases.
Common Urology Procedures and Conditions
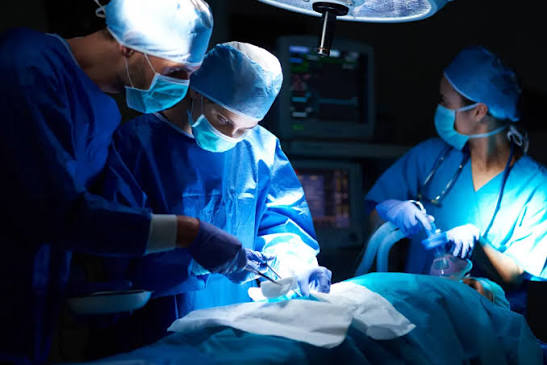
Urology procedures can range from quick, minimally invasive checkups to complex, robot-assisted surgeries, and are classified based on the specific condition being treated. Common conditions include prostate enlargement, kidney stones, male reproductive system conditions, and cancer screenings.
Urinary obstruction is one specific condition within this category. It typically arises when kidney stones, scar tissue, or tumours block the urinary tract, leading to infections, pain, and potential kidney damage. Common symptoms include blood in the urine and changes in urine output. The surgical approach depends on the location and severity of the blockage, ranging from temporary drainage procedures to open surgery, endoscopic surgery, laparoscopic surgery, or robot-assisted laparoscopic surgery — with cost varying accordingly depending on which approach is medically required.
Urinary tract complications, including urinary tract infections (UTIs), are another common condition covered under insurance. UTIs occur when bacteria enter the bladder through the urethra and are most common in women during perimenopause, menopause, and with the use of certain birth control methods. Common symptoms include a burning sensation while urinating, frequent urination with small amounts of urine, pelvic pain, and blood in the urine. If neglected, a UTI can spread to the kidneys and cause serious complications, including permanent kidney damage, narrowing of the urethra in men, low birth weight in infants born to affected pregnant women, and sepsis. Because complications can arise at any point and sometimes require emergency procedures, the unpredictability of the condition’s course is itself a reason to have coverage already in place rather than seeking it out once symptoms have escalated. Treatment often involves IV antibiotics and hospitalisation, both of which are typically covered.
Why Insurance Coverage Matters
Medical procedure costs for urology conditions are rising, and unplanned or emergency treatment can create significant out-of-pocket expense — potentially exhausting savings or forcing people to take loans or borrow from family and friends to arrange the required amount. Health insurance provides the necessary financial backup for both planned interventions and emergencies, while also protecting hard-earned savings from being drained by medical bills and offering a sum insured that helps absorb continued medical cost inflation over time. During a genuine emergency, this financial backup also has a psychological dimension: it lets patients and their families focus on the treatment decision itself rather than on how to arrange funds at short notice, which matters when a delay in deciding on surgery can affect outcomes.
Policies typically also give access to a network of hospitals for cashless treatment, flexible premium payment plans so beneficiaries do not feel an extra burden when paying them, online second opinions from reputed doctors, unlimited teleconsultations, and wellness programs that support early detection and better long-term management of these conditions — all of which matter because catching a urological issue early, before it progresses to a full obstruction or a kidney-threatening infection, generally means simpler and cheaper treatment. Cashless access through a network hospital also removes the need to pay upfront and seek reimbursement later, which can be a meaningful difference when a urology procedure is needed urgently rather than electively.
Network quality varies significantly by city and specialty — for maternity care specifically, checking a list of Best maternity hospitals in Bangalore in advance is just as useful as confirming urology network coverage.
What’s Typically Covered
Across urology procedures, urinary obstruction surgery, and urinary tract complications, insurance coverage commonly includes:
- Pre- and post-hospitalisation costs (consultation and diagnostic costs before admission, and follow-up care afterward)
- Inpatient hospitalisation expenses, including room rent, ICU charges, and surgery costs
- Doctor consultation fees and online/unlimited teleconsultations
- Daycare treatment expenses (for procedures needing less than 24 hours of hospitalisation)
- Ambulance charges (air and road, where applicable)
- AYUSH treatment costs and modern/advanced treatment costs
- Preventive health checkup coverage
- Domiciliary hospitalisation charges
- Vaccination expenses
- Physiotherapy and rehabilitation costs (specifically relevant for recovery from urinary tract complications and post-surgical urinary obstruction cases)
For urinary obstruction surgery specifically, this breadth of coverage matters because the actual procedure performed can vary enormously in cost — a temporary drainage procedure is a far smaller expense than an open or robot-assisted laparoscopic surgery, and a policy needs to be able to absorb either outcome depending on what the treating urologist finds once imaging and diagnosis are complete. Similarly, for urinary tract complications, coverage extending to physiotherapy and rehabilitation costs reflects the fact that a severe or repeated UTI that has caused kidney involvement may need a longer recovery process than the initial antibiotic course alone.
Choosing the Right Policy
When selecting insurance for urology-related conditions, it helps to check insurer reviews and ratings, understand the crucial policy terms, calculate the total payable premium, and review the claim settlement process and claim-settlement ratio of the insurer. It’s equally important to go through the network hospital list, the policy’s inclusions and exclusions, the waiting period, any unique offerings of the insurer, and available add-on coverage options. Taken together, these checks reveal not just whether a policy covers urology conditions on paper, but whether it will actually deliver a smooth claims experience when a real procedure is needed.
The same city-by-city research applies elsewhere too, since a list of Best Maternity hospitals in Hyderabad can help a family plan ahead regardless of which specialty they end up needing.
Purchasing a policy at an early age generally secures lower premiums, and choosing a reputable insurer with a high claim-settlement ratio improves the likelihood of assured claim approval. This matters particularly for urology conditions because several of them — kidney stones, prostate enlargement, recurring UTIs — tend to recur or worsen with age, so a policy bought early, before any diagnosis, avoids the pre-existing-disease waiting period that would otherwise delay a claim when the condition eventually needs treatment.
Prevention Alongside Insurance
For urinary tract complications specifically, simple preventive habits can reduce risk: drinking adequate fluids, maintaining proper hygiene, avoiding deodorant sprays near the urethral area, and using appropriate birth control methods. These habits are particularly relevant for women during perimenopause and menopause, and for anyone using birth control methods associated with a higher UTI risk, since these are the groups most commonly affected. None of these preventive steps eliminates risk entirely, which is exactly why they are best thought of as working alongside insurance rather than as a substitute for it — prevention reduces how often a claim becomes necessary, while insurance ensures that when treatment is needed, cost is not the deciding factor in how quickly it is sought.
Combined with a suitable health insurance policy that covers diagnosis, treatment, and follow-up, these preventive steps help manage both the health and financial risk associated with urology conditions, subject always to the specific terms and conditions of the chosen policy. The practical takeaway for anyone buying or reviewing a policy with urology coverage in mind is to check three things specifically: whether daycare and physiotherapy/rehabilitation costs are included (since not every basic plan covers these), what the waiting period is for any pre-existing urological condition, and whether the insurer’s network includes urologists and specialised centres capable of handling escalation from a minor blockage or infection to a more serious surgical case — because the right policy should be able to follow the condition wherever its treatment path leads, not just cover the simplest version of it.
